Australian Wine in China: How to Find Demand After the Restocking Phase

Following Beijing's tariff removal and the post-restocking normalization, Australian winemakers face a changed Chinese wine landscape. Discover actionable commercial routes to identify genuine pull demand across Tier 2/3 cities, white wine growth, and curated B2B matching.
Navigating China's Normalized Wine Landscape
When China removed anti-dumping and countervailing duties of up to 218.4% on Australian bottled wine on March 29, 2024, an initial surge of pipeline refilling followed, pushing bilateral wine trade back over $1 billion AUD according to Wine Australia. However, that initial replenishment phase is complete. The Chinese commercial landscape has structurally shifted. As Wine Australia's market reports point out, total Chinese wine consumption sits at roughly one-third of what it was five years ago, driven by changing consumer demographics, economic recalibration, and a shift away from lavish corporate banqueting toward intentional personal consumption.
For Australian brand owners, export managers, and regional associations navigating the broader Asia Wine Market, succeeding today is not about warehouse-push selling. It requires generating genuine retail and on-premise pull demand. Success demands targeted route-to-market strategies, precise regional distribution outside saturated Tier-1 hubs, diversification into rising categories like premium cool-climate whites, and disciplined B2B channel partner selection.
The Shift from Pipeline Restocking to Organic Pull Demand
During the initial 2024–2025 pipeline restocking phase, Australian exporters reconnected with historical importers eager to regain classic South Australian Shiraz and Cabernet Sauvignon labels. Yet, sell-through rates reveal a very different end-market reality:
- Banquet Contraction vs. Casual Occasions: Traditional high-end hospitality consumption tied to formal government and corporate gifting has slowed. Consumer occasions have pivoted toward casual social gatherings, intimate home dinners, and bistros.
- The Rise of Alternative Categories: While heavy red wines drove past booms, Wine Australia reported that Australian white wine exports surged by 77% in volume within 12 months after tariff removal, expanding white wine's export share to 15%. Chardonnays, Rieslings, and lighter reds (Pinot Noir and Grenache) are increasingly preferred by younger urban consumers.
- Inventory Discipline: Chinese importers and regional distributors now operate with lean balance sheets. Importers refuse to tie up capital in slow-moving container volumes without committed promotional, educational, and digital activation support from the producer.
To move beyond pipeline restocking and generate commercial velocity, Australian producers must pinpoint which regions and channels are actively expanding.
Where the Demand Is: Regional Markets and Emerging Channels
1. Beyond Tier-1: The Rise of Tier-2 and Dynamic Regional Hubs
Shanghai, Beijing, and Shenzhen are intensely saturated with global wine brands competing on razor-thin margins. In contrast, emerging commercial demand is consolidating in affluent regional provincial capitals and regional economic clusters such as the Greater Bay Area, Chengdu-Chongqing, Hangzhou, and Wuhan. Importers in these cities serve private dining clubs, regional boutique retailers, and corporate business networks that appreciate estate-grown stories rather than mass commercial labels.
2. Specialized On-Premise and Modern Bistro Culture
Modern Asian bistros, casual Western dining, and independent wine bars are expanding rapidly in Southern and Eastern China. These venues rarely purchase via large national commodity distributors; instead, they source via specialized fine-wine merchants who value provenance, sustainable viticulture, and food versatility.
3. Content-Driven Social Commerce & Digital Direct-to-Consumer Support
Platforms like Xiaohongshu (RED) and WeChat Mini Programs have transformed wine education and discovery. Successful brands do not dump stock onto commodity e-commerce; they equip their local distribution partners with tailored digital assets, short-form tasting clips, and lifestyle narratives that connect Chinese food pairings with Australian regionality.
Strategic Comparison: Traditional Importer vs. Specialized Direct-to-Channel
Choosing the right partner structure determines whether an Australian winery secures sustainable retail reorders or languishes in bonded warehouses.
| Commercial Attribute | Legacy Tier-1 National Importer | Specialized Regional Distributor / Boutique Partner | | :--- | :--- | :--- | | Primary Business Model | High-volume container drop, sub-distributor pass-through | Direct to on-premise, specialist boutique retail, curated e-commerce | | Inventory Risk | Requires deep margin cuts; high risk of dead stock if depletions stall | Operates on smaller, frequent mixed-pallet or consolidated orders | | Brand Stewardship | Minimal brand education; focused heavily on flagship SKUs | High hands-on sommelier training, localized tastings, active storytelling | | Portfolio Placement | Often lost in multi-thousand SKU international portfolios | Focus brand within a curated selection of 15–30 regional estates | | Payment Terms | Often demands extended credit terms (60–120 days) | Shorter credit windows, secure deposits, or LC-backed shipments |
Hypothetical Unit Economics: Evaluating Channel Strategy
To assess profitability between mass sub-distribution versus targeted regional allocation, consider this hypothetical financial model for an Australian producer shipping an allocation of 600 nine-litre cases (5,400 bottles of estate-level Shiraz/Chardonnay) to Mainland China.
Disclaimer: The following calculation is a clearly labelled hypothetical example based on contribution margin and total costs to illustrate channel economics; individual commercial agreements vary widely.
- Gross FOB Revenue (Ex-Adelaide): 5,400 bottles @ $14.00 AUD/bottle = $75,600 AUD
- Direct Winery Production & Packaging Costs: 5,400 bottles @ $5.50 AUD = $29,700 AUD
- Gross Product Margin: $75,600 - $29,700 = $45,900 AUD
Total Market Commercialization Costs:
- In-Market B2B Trade Exhibition & Travel Allocation: $11,000 AUD
- Localized Collateral & Digital Content Assets (WeChat/RED): $2,500 AUD
- In-Market Tasting Masterclasses & Sample Kits: $2,000 AUD
- Compliance, Customs Documentation & Label Registration: $1,400 AUD
- Total Commercial Costs: $16,900 AUD
Contribution Margin & Net ROI:
- Net Contribution Margin: $45,900 - $16,900 = $29,000 AUD
- Channel Contribution Margin Ratio: 38.36% ($29,000 / $75,600)
- Hypothetical Marketing ROI: (Net Contribution Margin $29,000 / Total In-Market Commercial Costs $16,900) × 100 = 171.6%
Key Strategic Insight: While the up-front investment in direct market trade shows and localized collateral increases direct costs compared to unassisted container trading, it protects producer pricing power, avoids predatory inventory fire-sales, and ensures steady repeat orders.
Step-by-Step Action Plan: Securing Depletions in 2026–2027
- Audit Your SKU Portfolio for Market Fit Do not export your entire domestic range. Curate an export portfolio comprising 1–2 distinctive cool-climate whites (e.g., Adelaide Hills Chardonnay, Eden Valley Riesling) to leverage white wine growth, alongside structured, food-friendly reds with authentic regional narratives.
- Review Regulatory & Customs Compliance Ensure CIF/FOB terms clearly delineate import duties, consumption tax, and VAT obligations. Confirm compliance with the General Administration of Customs of China (GACC) facility registration rules (Decree 248) and localized Chinese back-label requirements prior to maritime booking.
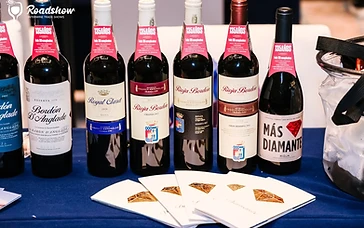
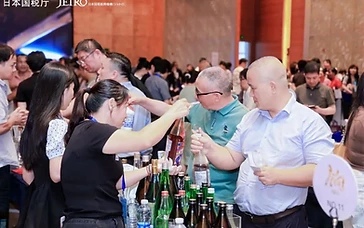
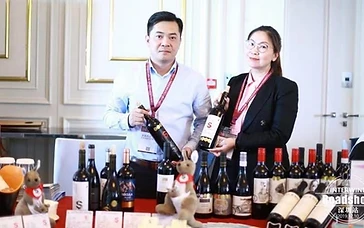
- Engage Verified Regional Buyers Face-to-Face Importers, corporate procurement leads, and sommelier networks in Southern China demand personal engagement. Meeting active buyers at verified trade platforms allows producers to pre-screen distribution partners based on their real warehouse footprint and sub-distribution reach.
- Commit to Joint Marketing Funds Structure distributor contracts with allocated co-marketing budgets pegged strictly to verified on-premise depletions rather than pure warehouse purchases.
Accelerate Your Market Entry with INTERWINE
Navigating China’s post-restocking landscape requires targeted, face-to-face engagements with verified regional distributors, direct importers, and hospitality buyers across Southern China and Southeast Asia.
Wineries, export groups, and regional brand collectives can accelerate distribution across Asia's high-growth commercial hubs by participating in the verified Interwine calendar:
- Guangzhou 2026: 16–18 November 2026
- Hanoi 2026 Roadshow: 20 November 2026
- Spring Guangzhou 2027: 7–9 May 2027 at the China Import and Export Fair Complex / Pazhou, Guangzhou
- Asia Roadshow 2027: Hanoi (11 May), Kuala Lumpur (13 May), Singapore (15 May), Bali (17 May)
- Vietnam 2027: 6–8 July 2027 at SECC, Ho Chi Minh City
- Autumn Guangzhou 2027: 31 October–2 November 2027 at the China Import and Export Fair Complex / Pazhou, Guangzhou
Position your brand before key importers and secure high-value commercial channels. Connect directly with verified distribution partners by reviewing our tailored Business Matching services, or submit your commercial reservation today to Become an Exhibitor.
Sources
- Wine Australia Market Bulletin & Export Insights
- Export Finance Australia: Australia Wine Exports Development
- Wine Business Magazine: Export Trends and Chinese Consumption Data
- Vino Joy News & WBM Online: China Import Customs Restocking Analysis
Key Takeaways
- —The initial post-tariff replenishment phase is complete; Australian winemakers must now focus on organic consumer pull demand rather than warehouse-push volume.
- —China's total wine consumption is approximately one-third of peak levels five years ago, shifting buying power from formal state banquets to casual, bistro, and personal dining.
- —Australian white wines are experiencing significant momentum, surging 77% in export volume post-tariff removal to represent 15% of shipments.
- —Tier-2 provincial capitals and dynamic regions across Southern China offer higher margin preservation and less competitive crowding than Tier-1 metropolises.
- —Face-to-face commercial discovery via platforms like Interwine Guangzhou provides the direct regional importer access required to secure disciplined depletions.
Frequently Asked Questions
What caused the decline in Australian wine shipment value following the post-tariff surge?
Following the lifting of duties in March 2024, exporters rushed shipments to refill depleted pipeline inventories. Once initial distributor stocks were established, shipment rates naturally normalized against lower underlying domestic consumption, which is approximately one-third of its volume from five years ago according to Wine Australia data.
Which wine styles are seeing the fastest growth in China post-restocking?
While premium Shiraz and Cabernet Sauvignon remain category anchors, lighter, more refreshing styles are growing rapidly. Australian white wine shipments increased by 77% in volume within a year after tariff removal, driven by demand for premium Chardonnay and Riesling in casual dining and modern bistro settings.
How can Australian wineries protect margins when working with Chinese distributors?
Rather than relying solely on high-volume national importers who demand steep FOB discounts, brands should partner with specialized regional distributors in Tier-2 hubs and dynamic clusters like the Greater Bay Area, backing allocations with targeted co-marketing funds tied directly to verified retail or on-premise depletions.
What regulatory requirements must Australian exporters satisfy before shipping?
Exporters must maintain valid registration with the General Administration of Customs of China (GACC) under Decree 248, meet specific Chinese back-label requirements regarding additives, health warnings, and importer details, and obtain appropriate export certification through Wine Australia.