How European Wineries Can Build an Asia Market Strategy
A commercial roadmap for European wineries navigating Asia's evolving wine trade. Learn market entry tiering, regulatory compliance, channel selection, and how targeted business matching drives sustainable export growth.
To succeed in Asia's commercial wine landscape, European wine producers must abandon the outdated view of the continent as a single, homogenous export destination. Winning in this territory requires a targeted, tiered market strategy that aligns production profiles—whether high-volume protected designation of origin (PDO) selections or boutique estate bottlings—with regional regulatory frameworks, distinct distribution tiers, and localized trade buyer expectations.
According to market analysis from Grand View Research (2026), the Asia Pacific wine market reached an estimated valuation of USD 102,426.5 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 10.7% from 2026 to 2033. However, trade reporting from Vino Joy News (2025) and WineNews (2025) demonstrates that aggregate European wine export volumes across several legacy Asian destinations encountered cyclical headwinds and volume contractions throughout 2024. For European export directors, these dynamics underline a fundamental reality: broad distributor-push models no longer work. Establishing a resilient, high-margin export footprint requires rigorous market segmentation, proactive compliance navigation, and direct access to pre-qualified buyers.
The Strategic Pivot: De-Averaging Asia’s Wine Markets
A commercially viable Asia market strategy begins by de-averaging the territory into functional tiers based on tariff regimes, category maturity, and route-to-market mechanics.
+---------------------------------------------------------------------------------------------------+
|                                 ASIA REGIONAL MARKET ARCHITECTURE                                  |
+------------------------------------+----------------------------------+---------------------------+
| MATURE VALUE HUBS                  | HIGH-VOLUME GROWTH REGIONS       | EMERGING SOUTHEAST NATIONS|
| Japan, South Korea, Hong Kong      | Mainland China                   | Vietnam, Thailand, SGP    |
| - Focus: Terroir & organic niches  | - Focus: Gifting, digital retail | - Focus: On-premise dining|
| - Barrier: High brand saturation   | - Barrier: GACC & CIQ customs    | - Barrier: Excise tariffs |
+------------------------------------+----------------------------------+---------------------------+
Tier 1: Mature Brand-Driven Hubs (Japan, South Korea, Hong Kong)
Japan and South Korea represent sophisticated consumer bases with advanced cold-chain infrastructure and established distribution networks. These markets prioritize traceability, organic viticulture, lower-alcohol formulations, and distinctive regional appellations. In Hong Kong, zero wine import duties establish the city as an essential commercial showcase and fine-wine re-export conduit for the wider region.
Tier 2: The Evolving Mainland China Market
Mainland China remains the demographic anchor of regional wine consumption. While speculative bulk buying has cooled, structural demand for premium imported European wines remains substantial. Winning commercial entry requires alignment with regional distribution networks across Tier 1 and emerging Tier 2 commercial hubs (such as Guangzhou, Shenzhen, Chengdu, and Hangzhou) alongside an understanding of integrated social-commerce channels.
Tier 3: High-Potential ASEAN Corridors
Southeast Asia's wine trade exhibits strong momentum. Research by Deep Market Insights (2026) projects the South East Asia wine market to grow from USD 12.25 billion in 2025 to USD 19.08 billion by 2034, registering a 5.15% CAGR. In markets like Vietnam and Thailand, growth is driven by tourism recovery, modern on-premise dining, and an expanding urban middle class. Navigating complex import licenses and varying excise tariffs across these markets requires strong relationships with established local importers.
Core Strategic Pillars for European Wineries
To build a defensible presence across Asian commercial markets, European producers must execute four baseline operational pillars.
1. Portfolio Adaptation and Route-to-Market Alignment
Exporting wineries frequently make the mistake of shipping their standard European catalog without tailoring formats, labels, or price architectures.
- Flavor and Varietal Profiles: While structured reds (such as Bordeaux blends, Tempranillo, and nebbiolo- or sangiovese-based wines) retain prestige in formal gifting circles, crisp whites, rosés, and sparkling wines are seeing rapid gains in southern Asian markets characterized by warm climates and seafood-driven culinary traditions.
- Packaging & Formats: Standard 750ml glass bottles remain dominant for premium retail. However, high-end gift packaging, customized bilingual back-labels, and temperature-resilient secondary packaging are non-negotiable considerations for preservation and shelf impact.
- Channel Definition: Wineries must determine whether their commercial objective is high-volume supermarket off-premise placement, boutique on-premise dining (Horeca), or curated e-commerce platforms. Each channel requires distinct margin allowances and distributor agreements.
2. Navigating Technical Regulations and Customs Compliance
Regulatory bottlenecks remain a frequent cause of costly supply chain disruptions for European exporters. Key areas of preparation include:
- Facility Registration: For Mainland China, producers must complete overseas production facility registration through the General Administration of Customs of China (GACC) under Decree 248/249 prior to dispatching shipments.
- Labeling Standards: Back-labels must precisely reflect local regulations, including accurate conversion of units, mandatory health statements, batch numbers, importer details, and additive declarations (such as sulfites) in local scripts.
- Documentary Precision: Certificates of Origin, phytosanitary analysis certificates, and bottling verification documents must align with customs HS Code 2204 classifications. Minor discrepancies can result in weeks of customs detention at regional maritime ports.
3. Sustainable Pricing and Margin Architecture
Export pricing must account for the compounding nature of logistics, maritime duties, warehousing, and intermediary distributor margins. A bottle leaving an Italian, Spanish, or French cellar door at €5.00 Ex-Works (EXW) can easily reach a retail price of €25.00 to €35.00 on Asian shelves after accounting for:
- Climate-controlled reefer shipping and port terminal fees
- Customs tariffs and ad valorem alcohol excise taxes
- Importer operational margins (typically 25% to 35%)
- Sub-distributor and retail markups (30% to 50%+)
European producers must establish transparent pricing floors to avoid channel conflict between general trade distributors, regional wholesalers, and parallel importers.
[Cellar Door (EXW)]
       │  + Reefers, Freight & Insurance
       ▼
[CIF Port of Entry]
       │  + Customs Duties, Excise & VAT
       ▼
[Landed Importer Cost]
       │  + Importer Margin (25-35%)
       ▼
[Wholesale Channel]
       │  + Distributor Margin (20-30%)
       ▼
[Final Retail / Horeca Shelf Price]
4. Partner Selection and On-the-Ground Trade Validation
Signing an exclusive master distribution agreement with the first interested regional entity carries major commercial risk. Once exclusivity is granted, European brands risk being shelved or neglected if the importer fails to invest in sales rep education or brand promotion.
Producers must evaluate potential distribution partners based on clear criteria:
- Active Regional Footprint: Does the importer possess temperature-controlled warehousing and cold-chain domestic transit networks?
- Portfolio Complementarity: Does your portfolio fill an active price or appellation gap, or will your labels compete with established house brands?
- Financial Health: Does the buyer have verifiable credit terms and an established network of active accounts across Tier 1 and Tier 2 cities?
Operationalizing Market Entry with Interwine
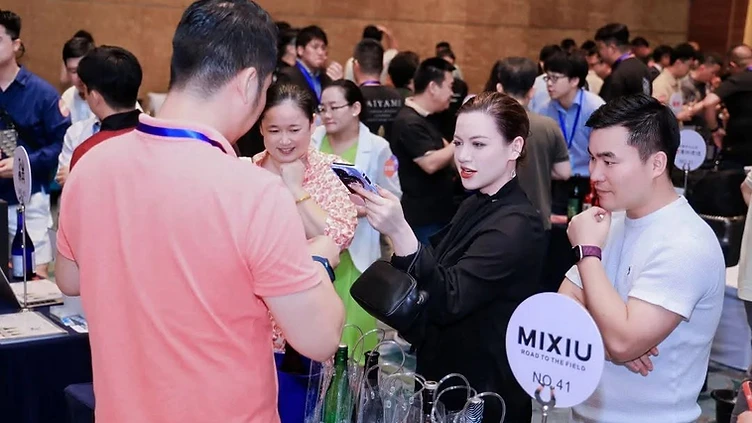
Rather than navigating Asian distribution landscapes through blind outreach or speculative sample shipments, leading European wineries deploy focused offline engagement to identify vetted commercial partners.
Interwine serves as China's premier international wine and spirits exhibition platform, providing verified access to over 50,000 professional buyers, distributors, regional wholesalers, and on-premise procurement executives annually.
                      COMMERCIAL CONVERSION FUNNEL

      [ Pre-Qualified Importers & Wholesalers ]
                         │
                         ▼
        [ Curated INTERWINE Business Matching ]
                         │
                         ▼
       [ On-Site Masterclasses & Sensory Tasting ]
                         │
                         ▼
     [ Formal Purchase Orders & Distribution Contracts ]
- Accelerate Importer Discovery: Leverage Interwine’s curated Business Matching services to secure pre-scheduled, one-on-one procurement meetings with top-tier Chinese and Asian importers actively seeking European agency agreements.
- Establish Trade Authority: Showcase regional appellation credentials directly to qualified trade buyers by participating as an exhibitor through Become an Exhibitor.
- Access Real-Time Market Intelligence: Evaluate consumer trends, shifting import patterns, and regulatory updates across the sector via Interwine's proprietary Market Insights division.
Conclusion
Building an enduring, high-return export footprint in Asia is entirely achievable for European wineries that combine disciplined market segmentation with regulatory compliance and proactive distributor development. By moving beyond transactional shipments and committing to structured regional partner validation, European producers can insulate their operations from domestic consumption declines and capture sustainable, long-term market share across Asia's dynamic wine trade.
Sources
- Grand View Research: Asia Pacific Wine Market Size & Outlook, 2026-2033
- Deep Market Insights: South East Asia Wine Market Size, Share & Trends Report By 2034
- Vino Joy News: EU Wine Exports: Declines Across Most Asian Markets in 2024 Except One
- European Commission: Prospects of the EU Wine Sector Report (2024)
- WineNews: From China to Japan, European Wine Slows Down in the Main Asian Markets (2025)
Key Takeaways
- —Asia is not a single market: European wineries must de-average strategy across mature hubs (Japan, South Korea, Hong Kong), volume drivers (Mainland China), and high-growth ASEAN corridors.
- —Data from Grand View Research (2026) indicates the Asia Pacific wine market reached USD 102.4 billion in 2025 and is projected to expand at a 10.7% CAGR through 2033.
- —Technical regulatory compliance—including GACC facility registration in China, precise local back-labeling, and HS Code verification—is critical to preventing costly port delays.
- —Export price architectures must account for multi-tier distribution margins, excise taxes, and climate-controlled freight to maintain competitive on-shelf parity.
- —Engaging via pre-vetted trade business matching platforms eliminates speculative distributor risk and accelerates verifiable commercial distribution contracts.
Frequently Asked Questions
What are the primary regulatory hurdles for European wineries exporting to China?
The most critical hurdle is completing overseas manufacturing facility registration under GACC Decrees 248 and 249 before dispatching shipments. In addition, labels must comply fully with Chinese national food safety standards (GB standards), detailing ingredients, sulfite declarations, importer contact information, and alcohol content in simplified Chinese.
How should European wineries structure pricing for Asian distribution channels?
Producers should adopt a bottom-up margin calculation beginning with Ex-Works (EXW) rates, factoring in climate-controlled reefer shipping, insurance, import tariffs, and local VAT/excise duties. Allow for a 25% to 35% margin for primary importers and an additional 30% to 50% for regional wholesalers and retailers to ensure healthy channel economics.
Why is nationwide exclusivity risky when partnering with wine distributors in Asia?
Asian markets, particularly China, are vast and fragmented by region. Many distributors specialize primarily in specific provinces, tiers of cities, or channels (such as e-commerce versus Horeca). Granting broad, non-performing national exclusivity can leave a European brand locked out of key high-consumption urban markets.
Which wine styles show the highest growth potential across Asian markets today?
While structured European red wines remain staples for corporate gifting and formal dining, there is rapidly rising demand for refreshing white wines, sparkling categories (such as Prosecco and Cava), organic and natural labels, and lower-alcohol styles driven by younger consumers and modern dining trends across East and Southeast Asia.
How does Interwine facilitate direct commercial relationships for wine exporters?
Interwine provides dedicated B2B trade platforms that connect international wineries directly with pre-screened Chinese and Asian importers, distributors, and retail procurement teams through curated business matching services, specialized trade masterclasses, and annual large-scale international exhibitions.