White Wine Distribution Opportunities in the Chinese Market
White wine is reshaping China's import beverage landscape. Discover commercial distribution channels, retail demand shifts, regulatory compliance requirements, and practical strategies for international producers.
For international wineries, white wine distribution opportunities in the Chinese market represent one of the clearest avenues for commercial growth in an otherwise cautious alcoholic beverage sector. Long overshadowed by heavy dry reds, white wine is shifting from a peripheral catering offering to a high-turnover retail and dining staple. According to retail data from the China Chain-Store & Franchise Association (CCFA) reported in 2025 by Vino Joy News, white wine captured 25% of supermarket wine sales in China while demonstrating an 8.5% year-on-year growth rate—outperforming every other wine sub-category. To capitalize on this dynamic, producers must look past outdated trade assumptions and build distribution models aligned with younger consumers, modern off-trade giants, and specialized on-premise dining networks.
The Commercial Shift: Moving Beyond China's Red-Dominant Paradigm
Historically, China's imported wine sector was anchored in gift-giving, corporate banquet customs, and a cultural affinity for red as an auspicious color, leaving white wine at a modest import footprint. However, import volume figures obscure actual consumer pull. Trade analysis shared at industry forums in 2025 indicated that while white wine comprised approximately 4% of China’s total wine import volume in 2024, its share of actual off-premise and on-premise consumption ranged between 10% and 20% (Vino Joy News, 2025).
Unlike cellared red wines that faced elevated distributor stockpiles after the 2024 tariff lift on Australian wines (MSA Asia, 2026), white wines operate on a high-inventory-turnover model. Importers prioritize white wines because bottles are intended for immediate, fresh consumption rather than speculative warehousing. The underlying demand is driven by shifting demographic behaviors: Gen Z and millennial drinkers, alongside a growing cohort of autonomous female buyers, show a marked preference for crisp, aromatic, and lower-tannin profiles that pair naturally with regional Chinese culinary traditions such as Cantonese seafood, Shanghainese cuisine, and fiery Sichuan hotpot.
Varietal Demand: Where Chinese Off-Trade and Direct Channels Align
Commercial success in Chinese white wine distribution requires precise varietal and price-point positioning. Mass consumer palates and commercial gatekeepers have prioritized two dominant varietals: Riesling and Sauvignon Blanc.
German Riesling
As reported by Wines of Germany China in 2025, German Riesling emerged as the number-one selling white wine across premium membership chains including Sam's Club and Aldi China (Vino Joy News, 2025). Furthermore, digital search traffic reveals intense organic interest: Riesling achieved over 15 million impressions on lifestyle search platform Xiaohongshu (RED) and ranked as the top searched wine keyword on e-commerce engine JD.com during summer retail peaks. Both dry and semi-sweet profiles capture traction, with off-dry and sweet entries (Kabinett and Spätlese styles) serving as approachable entry points for drinkers transitioning from ready-to-drink (RTD) beverages or beer.
Marlborough Sauvignon Blanc
New Zealand Sauvignon Blanc maintains exceptional brand recognition across tier-1 and tier-2 urban centers. Chinese buyers appreciate its vivid acidity, aromatic herbs, and tropical fruits, aligning with current lifestyle trends emphasizing light, clean, and crisp beverages. At enterprise retail chains like Metro China, Sauvignon Blanc direct-import sales posted a 6.62% year-on-year increase in 2024 (Vino Joy News, 2025).
Sweet Spots in Price Segmentation
Sales distribution data indicates that wines priced between RMB 100 and RMB 300 (roughly USD $14 to $42) generate approximately 45% of total retail white wine revenue, while the accessible tier below RMB 100 generates roughly 40% (Vino Joy News, 2025). For international wineries, entering the Chinese distribution ecosystem with accessible SKUs targeting RMB 99 to RMB 198 shelf prices provides the highest velocity for brand activation, while high-tier reserve lines (RMB 300+) can be leveraged in specialized bistro channels.
Navigating Distribution Channels: From Membership Supermarkets to Digital Retailing
Establishing viable routes to market requires diversifying across traditional importers, modern warehouse clubs, and direct digital commerce.
                                  ┌─────────────────────────────┐
                                  │   International Producer    │
                                  └──────────────┬──────────────┘
                                                 │
                     ┌───────────────────────────┴───────────────────────────┐
                     ▼                                                       ▼
       ┌───────────────────────────┐                           ┌───────────────────────────┐
       │ Traditional Importer/Tier-1│                           │   Cross-Border / Direct   │
       │     General Agent         │                           │    E-Commerce Platforms   │
       └─────────────┬─────────────┘                           └─────────────┬─────────────┘
                     │                                                       │
         ┌───────────┴───────────┐                                           │
         ▼                       ▼                                           │
┌─────────────────┐     ┌─────────────────┐                                  │
│ HORECA & Urban  │     │ Warehouse Clubs │                                  │
│ Wine Bistros    │     │(Sam's, Aldi)    │                                  │
└─────────────────┘     └─────────────────┘                                  │
         │                       │                                           │
         └───────────────────────┼───────────────────────────────────────────┘
                                 ▼
                     ┌───────────────────────────┐
                     │  End Consumer / On-Premise│
                     └───────────────────────────┘
Modern Warehouse Retail and Direct-Sourcing
Membership-driven supermarket models such as Sam's Club, Costco, Metro China, and Aldi have consolidated massive wine sales volumes in mainland cities. These retailers bypass multilayered sub-distributor networks, preferring direct sourcing or streamlined single-tier distributor partnerships. Brands targeting these accounts must provide robust supply scalability, consistent organoleptic specs, and competitive FOB terms.
The On-Premise Shift: Casual Bistros and Wine Bars
Traditional banquet dining has yielded ground to informal wine bistros, modern izakayas, and casual Western/fusion restaurants throughout Guangzhou, Shenzhen, Shanghai, and Chengdu. Master Sommelier Lu Yang observed that a semi-sweet white or vibrant Sauvignon Blanc has evolved into a mandatory fixture on casual dining lists (Vino Joy News, 2025). Importers supplying this sector look for boutique estates with narrative appeal, distinctive labels, and food versatility.
E-Commerce and Social Live Selling
According to analysis from Dezan Shira & Associates citing IWSR, China's online alcohol market is projected to expand at a compound annual growth rate (CAGR) of 6% between 2022 and 2027, ultimately accounting for approximately 40% of global online beverage alcohol sales (China Briefing, 2025). White wine captures significant online attention via channels like Douyin, JD.com, and Tmall. However, success online requires disciplined Minimum Advertised Price (MAP) management. Producers must prevent non-authorized discount liquidations from undercutting brick-and-mortar pricing.
To discover current macro shifts and buyer demographics, review our dedicated Market Insights.
Regulatory Compliance and Cold-Chain Logistics
Distributing white wine in China requires strict adherence to customs oversight and specialized logistics to preserve fresh organoleptic qualities:
- GACC Facility Registration (Decree 248/249): All foreign food and alcoholic beverage manufacturing and storage facilities must obtain direct registration with the General Administration of Customs of China (GACC) via the Single Window platform prior to export. Unregistered production runs face customs border refusal.
- Mandatory Chinese Back-Labels: Commercial labels must accurately declare total dry extract, alcoholic strength, allergen notices (e.g., sulfur dioxide), imported batch details, and the registered Chinese domestic importer.
- Cold-Chain Logistics Execution: Because white wine is sensitive to ambient thermal degradation, high summer temperatures in South China ports (such as Shenzhen and Guangzhou) present critical risks. Producers should mandate temperature-controlled reefers during sea freight and audit regional distributors on their air-conditioned transit practices.
Strategic Steps to Meet Qualified Chinese Buyers
Breaking into China's evolving white wine landscape requires direct commercial engagement with vetted regional importers rather than waiting for inbound digital inquiries. Wineries must build local credibility by adopting a targeted market approach:
- Select an Intuitive Chinese Brand Name: Create a phonetically pleasing, culturally resonant Chinese brand name and secure intellectual property trademark rights across Classes 33 and 35 before shipment.
- Equip Distribution Partners with Localized Education: Chinese sommeliers, retail staff, and sales reps require education modules detailing acidity balance, chilling recommendations, and local cuisine pairing mechanics.
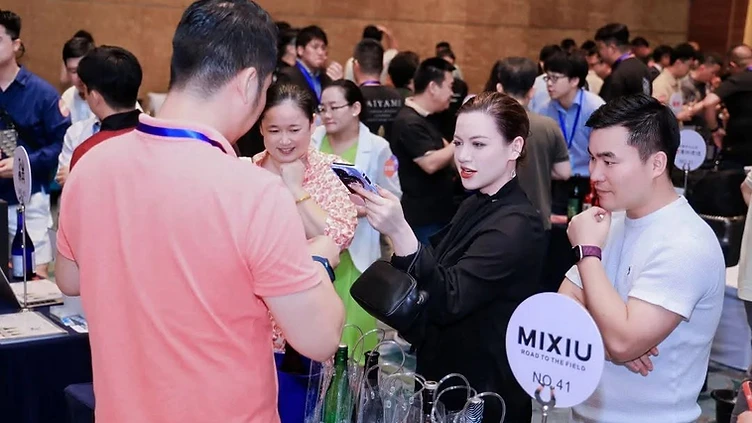
- Engage Face-to-Face at Mainland Wine Fairs: Exhibiting directly in key regional consumption gateways remains the primary method for signing credible regional partners.
International producers seeking direct meetings with mainland importers, supermarket procurement heads, and regional sommeliers should evaluate opportunities to Become an Exhibitor at upcoming editions of Interwine China in Guangzhou. Producers ready to build targeted buyer relationships can optimize their visit through scheduled Business Matching meetings and secure professional travel support via Invitation Letter and Visa Support.
Conclusion
The expansion of white wine consumption in China is an enduring structural realignment driven by female professionals, younger demographics, and modern retail innovation. Wineries that supply approachable pricing, crisp flavor profiles, secure regulatory filings, and active promotional support will capture durable market share in Asia's largest alcohol market.
Sources
- Vino Joy News (2025) - China's White Wine Boom: Who Will Come Out on Top?
- China Briefing by Dezan Shira & Associates (2025) - China’s Wine Market Outlook: Trends and Opportunities
- MSA Asia Advisory (2026) - Wine Market in China: Trends, Growth, and Consumer Preferences
- Università Ca' Foscari Venezia (2019) - The Evolution of the Chinese Wine Market
Key Takeaways
- —White wine accounts for 25% of supermarket wine sales in China with an 8.5% annual growth rate, vastly outperforming broader wine categories.
- —While white wine represented roughly 4% of China's import volume in 2024, its share of domestic consumption is estimated between 10% and 20% due to rapid inventory turnover.
- —German Riesling and New Zealand Sauvignon Blanc dominate category awareness, led by membership warehouse channels such as Sam's Club, Metro China, and Aldi.
- —The RMB 100–300 price bracket represents 45% of retail white wine sales, making mid-tier commercial offerings the sweet spot for new market entrants.
- —Temperature-controlled logistics and early GACC Decree 248 facility registrations are critical compliance prerequisites for fresh wine preservation.
Frequently Asked Questions
What is driving the growth of white wine in China?
Growth is driven primarily by younger consumers and female wine drinkers who favor refreshing, aromatic profiles over high-tannin reds. In addition, white wine pairs naturally with light regional Chinese cuisines like Cantonese and seafood dishes, and off-premise membership retailers such as Sam's Club and Aldi have actively expanded their white wine selections.
Which white wine varietals are most popular among Chinese buyers?
German Riesling and Marlborough Sauvignon Blanc are currently the most popular varietals. Riesling enjoys strong demand in both dry and off-dry or semi-sweet profiles across retail and social media platforms, while Sauvignon Blanc is established in high-end dining and casual wine bistros.
What price segment delivers the highest sales volume for white wine in China?
Wines priced between RMB 100 and RMB 300 account for approximately 45% of retail sales, while value offerings under RMB 100 represent around 40%. The RMB 100–199 range represents the optimal commercial sweet spot for new market entrants seeking volume through modern retail channels.
How do import regulations impact white wine shipments to China?
Producers must be registered with China Customs under GACC Decree 248 before dispatching shipments. In addition, wines must carry compliant Chinese back-labels detailing allergens, importer credentials, and product specifications. Because white wines are sensitive to heat degradation, temperature-controlled container freight is essential during summer port arrivals.
How can international white wine producers connect with verified Chinese distributors?
Producers can partner with established trade exhibitions such as Interwine China in Guangzhou, take part in structured business matching programs, and engage directly with regional importers, bistro operators, and supermarket procurement managers.