Wine Consumer and Channel Trends in Singapore
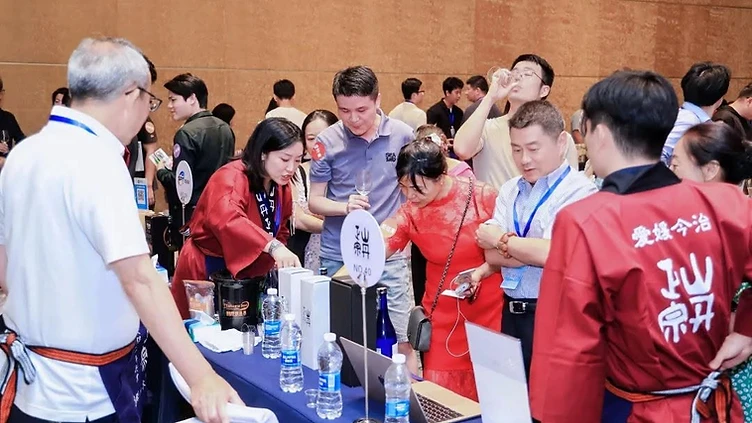
Discover the latest wine consumer and channel trends in Singapore. Learn how premiumisation, natural wines, HoReCa procurement, and duties shape market entry.
For international wine producers targeting Asia-Pacific, Singapore represents the premier commercial showroom and distribution springboard for Southeast Asia. While modest in domestic population, the city-state boasts one of the highest per-capita GDPs in the world and serves as a regional financial, trade, and gastronomy hub. According to market analysis published by WMStrategy in 2024, the Singapore wine market grew at a compound annual growth rate (CAGR) of 6.13% between 2020 and 2024, driven by affluent consumer spending, premium on-premise dining, and sophisticated retail channels.
However, expanding into Singapore requires navigating high excise duties, rising operational costs, and intense competition from established Old and New World brands. To secure sustainable distribution, brand owners must understand evolving consumer preferences—such as the surge in low-intervention wines and category polarization—as well as the operational mechanics governing Singapore's on-trade, specialist retail, and e-commerce distribution ecosystems.
Singapore Wine Market Dynamics: Size, Premiumisation, and Volume Realities
Singapore operates on an import-dependent, value-over-volume model. Unlike high-volume consumer markets across developing Asia, Singapore’s market expansion is propelled almost entirely by premiumisation and selective trade consumption.
Research published by Euromonitor International in late 2024 highlights that the Singapore alcohol market is experiencing noticeable polarization. Consumers are dividing into two primary camps: those seeking high-end, premium dining experiences where price resistance is minimal, and price-conscious shoppers managing inflation and high local taxes through targeted promotional purchases. Concurrently, wellness-driven moderation is shifting consumer drinking habits, resulting in slower overall volumetric growth alongside a sharp climb in average transaction value per bottle.
For international wineries, these dynamics mean that low-end, commodity-grade table wines face steep commercial headwinds. Under Singapore Customs regulations, alcoholic beverages are levied an excise duty calculated on pure alcohol content (SGD $88.00 per liter of pure alcohol as of official excise schedules), coupled with an 8%–9% Goods and Services Tax (GST). When logistics, warehousing, importer margins, and on-premise markups are applied, an entry-level wine struggles to offer compelling value against quality benchmarks. Conversely, mid-to-high tier wines ($25–$80+ retail) absorb fixed taxes more efficiently, delivering sustainable operating margins across both on-trade and independent retail.
Shifting Wine Consumer Profiles and Tasting Preferences
Singaporean wine consumers are among the most educated and well-traveled in the Asia-Pacific region. Over the past five years, consumption patterns have diversified significantly beyond classical Bordeaux and Australian Shiraz.
The Rise of Natural, Organic, and Low-Intervention Labels
Consumer demand for authenticity and environmental transparency has accelerated. According to Singapore trade analysis published by Benchmark Wines in 2025, the natural and low-intervention wine movement has evolved from a niche subculture into a core purchasing trend across urban wine bars and boutique retail. Globally, the organic wine sector is expanding at a projected CAGR of 10.3% from 2024 to 2030, and Singapore is capturing this momentum directly through younger demographic cohorts (millennials and Gen Z) who prioritize sustainable viticulture, minimal sulfur additions, and distinctive production narratives.
Stylistic Evolution: White, Sparkling, and Cool-Climate Varieties
While red wine historically dominated Asian dining tables, Singapore's year-round equatorial climate and thriving culinary scene have catalyzed strong growth for expressive white wines, crisp rosés, and sparkling labels. Dry and aromatic Rieslings, Albariño, cool-climate Chardonnays, and mineral-driven Chenin Blancs are finding consistent placement on contemporary tasting menus. Sommelier-led pairings in modern Asian, seafood, and fusion dining establishments demonstrate that consumers value acidity, food-matching versatility, and lower tannin weight.
Moderation and Wellness Trends
As noted in Euromonitor International's industry report, "nolo" (no-and-low alcohol) alternatives and lighter-alcohol styles (ranging from 10.5% to 12.5% ABV) are gaining visible retail shelf space. Urban professionals increasingly treat wine as an intentional lifestyle pursuit rather than purely a social intoxication vehicle, prompting procurement teams to seek lighter, drinkable styles with full sensory complexity.
Channel Analysis: Navigating Singapore’s Distribution Architecture
Successfully scaling a brand in Singapore requires targeted channel allocation. Producers must evaluate the distinct operational demands of HoReCa, modern retail, independent specialists, and direct-to-consumer digital platforms.
1. On-Premise / HoReCa (Hotels, Restaurants, and Cafés)
The on-premise segment constitutes the primary brand-building engine in Singapore. With one of the world's highest concentrations of Michelin-starred restaurants, luxury hotel groups (e.g., Marina Bay Sands, Raffles), and progressive independent gastro-bars (such as Telok Ayer, Keong Saik, and Club Street precincts), HoReCa visibility validates brand credibility across the broader ASEAN market.
- Procurement Gatekeepers: Buying decisions are controlled by certified head sommeliers, corporate food and beverage (F&B) directors, and specialist on-premise importers.
- Commercial Reality: Wine lists are fiercely competitive and rotate frequently. Importers servicing HoReCa demand robust promotional support, by-the-glass pricing incentives, staff masterclasses, and consistent vintage availability.
2. Specialist Independent Wine Merchants and Cellars
Boutique retailers and cellar shops cater to Singapore’s connoisseurs and private collectors. Unlike mainstream grocery outlets, these merchants prioritize boutique family estates, single-vineyard bottlings, and rare allocations.
- Target Audience: Sophisticated corporate professionals, private event hosts, and serious collectors.
- Channel Mechanics: Independent merchants emphasize storytelling, tasting events, and personal client curation. Placement here requires compelling provenance, producer engagement, and distinct shelf-talker value rather than massive marketing budgets.
3. Modern Off-Trade Retail (Supermarkets and Hypermarkets)
Large-scale retail chains—including FairPrice Finest, Cold Storage (DFI Retail Group), and Sheng Siong—account for the bulk of everyday household volume.
- Listing Barriers: Established grocery retail imposes strict commercial conditions, including listing fees, slotting charges, mandatory promotional rebates, and consignment payment windows.
- Portfolio Fit: Commercial, approachable labels with scalable production and established brand recognition thrive in this tier, while artisanal, low-volume producers often find the payment terms and margin dilution prohibitive.
4. Wine E-Commerce and Omnichannel Retailing
Online wine purchasing expanded rapidly following pandemic retail shifts and has stabilized as an integral channel. Dedicated wine platforms, omnichannel retailers, and rapid delivery operators offer an extensive catalog of international references directly to consumer doorsteps.
- Consumer Behavior: Digital shoppers cross-reference Vivino ratings, global price benchmarks, and critic reviews in real-time.
- Challenge: Price transparency on digital platforms can create friction with on-premise buyers if off-trade consumer pricing undercuts restaurant wine lists. Producers must maintain strict channel pricing parity.
Strategic Channel Comparison for Brand Entry
| Channel | Volume Potential | Margin / Price Realization | Entry Barrier | Primary Target Consumer | | :--- | :--- | :--- | :--- | :--- | | HoReCa (Fine Dining & Wine Bars) | Moderate | High (supports premium pricing) | High (Sommelier gatekeeping, vintage consistency) | Affluent locals, business executives, international tourists | | Specialist Boutique Retail | Low – Moderate | High | Moderate (requires authentic story & quality rating) | Enophile collectors, gifting clients, educated enthusiasts | | Supermarket Chains (Finest / Cold Storage) | High | Moderate – Low (promotional pressures) | Very High (listing fees, volume requirements) | Everyday household consumers, casual entertaining | | E-Commerce & DTC Platforms | Moderate | Moderate | Low – Moderate (logistics and warehouse setup) | Tech-savvy professionals, value-seeking bulk buyers |
Singapore as an ASEAN Springboard: Opportunities and Risks
Regional market intelligence published by Source of Asia in 2024 identifies Singapore as the most transparent, legally secure, and low-risk entry market in Southeast Asia. The country's strict rule of law, clear customs processes, and zero corruption make trade transactions predictable.
Commercial Advantages
- Re-Export Hubbing: Singapore's bonded warehousing infrastructure and Free Trade Zone facilities enable producers to use the island as a central consolidation and cold-storage hub for secondary distribution into Vietnam, Thailand, Malaysia, and Indonesia.
- Regional Influence: Tastemakers, beverage directors, and hospitality executives across Southeast Asia look to Singapore’s culinary scene as the regional benchmark for wine trends.
Key Market Risks
- Distributor Saturation: Singapore’s importer landscape is crowded with established agencies handling hundreds of global labels. New brands face the risk of being listed on a distributor portfolio without active sales push.
- High Holding Costs: Climate-controlled bonded storage and commercial real estate in Singapore are among the most expensive in Asia, forcing local importers to maintain lean inventory and order frequently in smaller palette drops.
- Tight Margin Thresholds: Because of specific excise duties, brand owners must be prepared to price FOB (Free on Board) shipments competitively to allow importers room for sustainable markups.
Commercial Playbook: Step-by-Step Market Entry
For international brand owners ready to access Singapore’s lucrative market, execution discipline is decisive:
- Audit Portfolio Alignment: Screen SKUs against Singaporean climatic and dining preferences. Emphasize expressive whites, mineral-driven rosés, low-intervention reds, or recognizable premium expressions over heavy, entry-level commercial reds.
- Target Dedicated Specialist Importers: Rather than pursuing broad-line beverage conglomerates where an independent brand may become inactive, partner with focused mid-sized importers specialized in your specific category or channel.
- Participate in Curated B2B Platforms: Direct engagement with certified commercial buyers reduces market entry timelines. Utilizing structured Business Matching services allows wineries to pitch directly to vetted Singaporean importers, sommeliers, and purchasing directors looking for specific appellations.
- Explore Regional Trade Exhibitions: Gaining wider exposure across Asian buyers requires active participation in regional industry forums. Review opportunities to Become an Exhibitor or consult the latest Market Insights to understand procurement schedules ahead of peak Asian hospitality seasons.
- Provide On-the-Ground Activation Support: Ensure commercial viability by supporting distributor tasting flights, staff educational seminars, and winemaker dinner activations across Singapore’s key dining precincts.
Sources
- Euromonitor International: Wine in Singapore Report
- Euromonitor International: Wine in Singapore Category Analysis
- Benchmark Wines: Wine Trends in Singapore 2025
- Source of Asia: Wine & Spirits in ASEAN Market Comparison
- WMStrategy: Singapore Wine Market Size and Structure
Key Takeaways
- —Singapore's wine market grew at a 6.13% CAGR between 2020 and 2024 according to WMStrategy, driven primarily by premiumisation and gastronomy rather than mass volume.
- —Specific alcohol excise duties (SGD $88 per liter of pure alcohol) make low-tier entry wines economically uncompetitive, favoring mid-to-premium bottles ($25+ retail).
- —Natural, organic, and low-intervention wines are transitioning from niche subcultures to mainstream listings across Singapore's leading wine bars and restaurants.
- —White and sparkling wines suited to the equatorial climate—notably Riesling, cool-climate Chardonnay, and crisp sparkling—are steadily gaining market share from heavy reds.
- —Singapore serves as Southeast Asia's central bonded logistics and re-export hub, providing a secure launchpad for wider ASEAN distribution.
Frequently Asked Questions
How are wine import duties calculated in Singapore?
Singapore levies customs excise duties on wine based on pure alcohol content, calculated at SGD $88.00 per liter of pure alcohol (alcohol by volume x bottle volume x $88), in addition to the prevailing standard Goods and Services Tax (GST) applied to the combined CIF (Cost, Insurance, and Freight) and duty value.
Which wine styles are growing fastest among Singapore consumers?
Demand is growing rapidly for organic, biodynamic, and natural wines, alongside cool-climate whites (such as German and Austrian Rieslings, dry Chenin Blanc), refreshing sparkling wines, and lower-ABV styles that complement Singapore's equatorial climate and diverse dining culture.
What is the primary channel for building wine brand equity in Singapore?
The premium on-premise (HoReCa) channel—comprising Michelin-starred establishments, boutique wine bars, and luxury hotels—is the most crucial platform for establishing brand prestige and regional visibility before scaling into specialty retail or e-commerce.
Why is Singapore considered a springboard for the Southeast Asian wine market?
Singapore offers world-class bonded warehousing, transparent customs, strong legal protections, and a sophisticated regional buyer network, making it an ideal hub to test consumer response and re-export wine shipments across neighboring ASEAN markets like Vietnam, Thailand, and Malaysia.