Industry Interview: A International winery on Market selection priorities

In this industry interview, an international winery export director breaks down market selection priorities, route-to-market alignment, regulatory risks, and strategies for engaging Asian buyers in 2025.
International winery commercial directors are overhauling export allocation models to defend operating margins in an increasingly volatile global landscape. According to an econometric analysis published in Agricultural Economics – Czech in December 2024, export performance and export intensity for wine producers correlate directly with precise strategic and channel adjustment between the winery and destination markets, rather than sheer production volume. Concurrently, data highlighted by Wine Economics and Policy in 2025 reveals that while global production and consumption volumes have experienced contraction, cross-border wine trade flows have remained fiercely competitive, rewarding producers that execute disciplined, multi-criteria country selection.
To examine how estate and commercial producers are adapting, we spoke with a veteran Commercial Export Director overseeing a global portfolio across Europe, the Americas, and Asia. This industry interview reveals the operational priorities governing international market selection, shifting importer expectations, regulatory hurdles, and practical routes to building distribution in high-value territories.
The Strategic Pivot: Shifting Beyond Legacy Volume Markets
Interwine Editorial Team: Global wine distribution has faced major logistical and tariff realignments. When evaluating new target countries today, what are your primary criteria for commercial viability?
Export Director: Five years ago, international expansion for mid-to-large wineries followed a predictable path: maximize allocations to the United States, establish retail shelf presence in the United Kingdom, and secure high-volume container shipments into Northern Europe. Today, that playbook carries heavy structural margin risks.
As reported by IWSR Drinks Market Analysis in 2024, the wine sector faces ongoing structural consumption shifts and recruitment challenges among younger demographics across mature Western economies. Compounding this, mature retail markets are plagued by aggressive discounting, retail consolidation, and rising logistics duties.
Our market selection framework now applies a three-layer filter before allocating export capital:
- Net Realized Value Per Liter: Gross export volume is a vanity metric. We prioritize destination markets where imported wine commands a sustainable premium above freight and compliance tariffs.
- Channel Friction and Route-to-Market Diversity: Markets dominated by monopolistic supermarket purchasing desks squeeze winery margins. We target regions offering vibrant independent retail, upscale HoReCa (Hotel, Restaurant, and Catering), and digital direct-to-consumer networks.
- Regulatory Predictability and Turnaround: We evaluate customs clearance speed, labeling adaptability, and currency stability. If an emerging market presents excessive inventory holding risks due to bureaucratic delays, the internal rate of return erodes immediately.
This strategic alignment reflects the empirical findings in the Agricultural Economics 2024 study: export probability hinges on channel adjustment. Wineries cannot simply dump excess inventory into new borders; the product tier must match the buying patterns and distributor capacity of the importing region.
Evaluating Asia-Pacific and China: Growth Dynamics and Route Calibration
Interwine Editorial Team: With major market realignments taking place across the Pacific Rim, how is your estate positioning its allocations for mainland China and broader Asian distribution hubs?
Export Director: Asia-Pacific remains one of the most commercially attractive, yet misunderstood, regions. Following the stabilization of import tariffs and the restructuring of trade flows, China has re-emerged as an essential strategic focus for producers committed to disciplined brand building. According to trade flow research from the International Trade Council’s 2024–2025 Global Wine Trade Report (published March 2025), customs data across major producing nations reflects steady realignment toward diversified regional hubs, with high demand for premium packaged goods classified under HS Code 220421.
However, entering China requires an entirely different operational mindset compared to a decade ago. The era of speculative, passive container buying has ended. Modern Chinese wine importers, regional sub-distributors, and corporate procurement directors demand:
- Strict Channel Exclusivity: Importers will not invest in marketing an estate if grey-market eCommerce platforms undercut wholesale pricing.
- Educational and Event Collateral: Buyers look for producers willing to provide verified regional origin storytelling, customized digital assets, and structured consumer masterclasses.
- Localized Packaging Compliance: Immediate readiness to comply with General Administration of Customs of China (GACC) facility registration, ingredient traceability standards, and Mandarin-compliant back-label regulations.
To navigate these regional realities, commercial winery teams rely directly on specialized macro-level research and trade updates published in Market Insights to calibrate shipping volumes against real on-the-ground consumption patterns.
Distributor Due Diligence: Securing Resilient Commercial Partners
Interwine Editorial Team: Distributor turnover is a recurring vulnerability for exporting wineries. What criteria do you use to vet an import partner before granting territorial distribution rights?
Export Director: An overseas distributor contract is only as strong as the partner's actual cash-flow discipline and active account coverage. When we interview potential importers at exhibitions or during commercial trade missions, we evaluate four concrete variables:
| Evaluation Metric | Red Flag | Positive Commercial Indicator | | :--- | :--- | :--- | | Portfolio Breadth | Excessive direct competitors in the same origin appellation and price point. | Complementary regional catalog; clear tiered pricing gap for our SKUs. | | Payment and Cash Flow | Demanding extended consignment terms (120+ days) on maiden container orders. | Letters of Credit (LC) or standard 30-to-60-day terms with structured milestone deposits. | | Channel Penetration | Claims of "nationwide distribution" without dedicated regional sub-agent networks. | Documented accounts across tier-1 dining groups, boutique wine shops, or high-end retail. | | Stock Depletion Velocity | Lack of secondary promotional support; passive warehouse stocking. | Active trade tastings, sommelier engagement, and defined bi-annual depletion targets. |
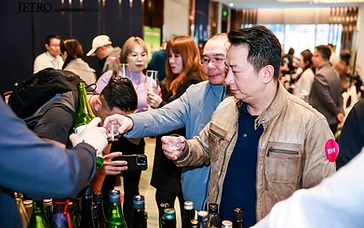
Producers seeking reliable partners must move beyond remote email exchanges. Face-to-face commercial alignment is indispensable. Participating in pre-vetted buyer-seller forums such as Business Matching allows export executives to review importer financial backgrounds, channel focus, and annual purchasing volume before entering formal negotiation.
Overcoming Regulatory and Supply Chain Friction
Interwine Editorial Team: Beyond finding the right partner, what operational roadblocks consistently threaten new market execution?
Export Director: Regulatory divergence and cold-chain integrity are our primary concerns. As reported by drinks business analyst Richard Siddle in The Buyer in April 2026, international wineries and merchant groups must maintain agile supply models and boots-on-the-ground representation to mitigate rising tariff spikes, cross-border freight friction, and localized import barriers.
For example, temperature abuse during transshipment can destroy an entire consignment of premium wine. Ensuring reefer container availability and temperature-logging telemetry during maritime transit is non-negotiable.
Furthermore, regulatory documentation must be precise. Discrepancies between the Certificate of Origin, phytosanitary certificates, analysis certificates, and back-label declarations lead to bonded warehouse impoundment, accruing demurrage costs that can wipe out operating margins. Estates expanding into Asia must work with logistics partners who possess demonstrable expertise in regional ports of entry.
Practical Steps: Turning Trade Presence into Commercial Contracts
Interwine Editorial Team: For winery executives, trade directors, and professional buyers finalizing their seasonal sourcing calendars, what are the recommended operational next steps?
Export Director: Avoid fragmented, speculative market testing. Successful international expansion requires focused physical engagement in strategic commercial centers where high-caliber buying power converges.
- Audit Sourcing Capacity: Importers should evaluate their current portfolio gaps across specific varietals, regions, and price bands. Reviewing structured supplier lists through an Exhibitor Directory enables commercial buyers to schedule pre-qualified meetings with audited wineries.
- Participate in Specialized Industry Events: Direct trade show participation remains the highest-ROI channel for evaluating liquid quality, packaging integrity, and executive commitment. Coordinating trade schedules around specialized masterclasses and commercial forums at Interwine Events guarantees efficient buyer-producer interaction.
- Execute Face-to-Face Contract Negotiations: Remote samples rarely close enterprise distribution deals. Decision-makers must plan professional travel to primary exhibition floors to finalize commercial pricing, exclusivity terms, and marketing support frameworks.
Qualified trade professionals, regional distributors, and enterprise buyers preparing their sourcing pipeline can secure direct commercial access and credentialed entry when they Book Your Visit to upcoming industry trade showcases.
Summary of Key Takeaways
- Margin over Volume: Sustainable market selection prioritizes net realized price per liter and structural channel alignment above headline export volumes.
- Asia’s Strategic Position: The Asia-Pacific corridor, anchored by expanding purchasing power in Greater China, demands strict channel exclusivity, tailored marketing, and full compliance with import food safety regulations.
- Distributor Vetting: Successful long-term partnerships depend on audited cash flow, complementary portfolio positioning, and transparent secondary sales networks.
- In-Person Trade Forums: Efficient market penetration is built through structured business matching, on-site tastings, and verified trade interactions rather than cold outreach.
Sources
- Agricultural Economics – Czech (2024): Market entry strategy and export destination in the Spanish wine industry – https://agricecon.agriculturejournals.cz/pdfs/age/2024/12/03.pdf
- Wine Economics and Policy (2025): State of the International Wine Markets in 2024 – https://oaj.fupress.net/index.php/wep/article/view/17914
- IWSR Drinks Market Analysis (2024): Seven key trends that will shape the global wine industry in 2024 – https://www.theiwsr.com/insight/seven-key-trends-that-will-shape-the-global-wine-industry-in-2024/
- International Trade Council (2025): 2024–2025 Global Wine Trade Market Research Report – https://tradecouncil.org/wp-content/uploads/2025/04/2024-2024-Wine-Report.pdf
- The Buyer (2026): Analysis: Why global drinks industry is opening up like never before – https://www.the-buyer.net/insight/analysis-why-the-global-drinks-industry-is-opening-up-like-never-before
Key Takeaways
- —Winery export strategies are pivoting from generic volume-driven allocation to margin-protective country selection based on net realized value per liter.
- —Strategic channel adjustment between the winery product tier and destination market characteristics is essential for sustained export intensity.
- —Importers in China and wider Asian markets prioritize brand exclusivity, regulatory readiness, and localized promotional support over unbranded bulk supply.
- —Rigorous distributor due diligence must screen for cash-flow reliability, on-premise penetration, and active depletion programs.
- —In-person commercial matching platforms and credentialed industry trade fairs deliver significantly higher conversion rates than unverified cold outreach.
Frequently Asked Questions
What is the most critical metric wineries use when selecting new export markets?
Rather than evaluating total national consumption alone, experienced commercial directors prioritize net realized value per liter. This metric accounts for tariffs, logistics overhead, distributor margin expectations, and retail promotional spend to determine actual profitability.
Why is strategic channel adjustment important for wine exporters?
As demonstrated in agricultural trade research, export success relies on matching a winery's specific portfolio tier with the primary sales channels of the target market. A winery structured for premium HoReCa accounts will struggle in destinations dominated exclusively by low-margin supermarket monopolies.
What specific requirements do Asian wine importers have for new international estates?
Importers across key Asian markets such as China prioritize strict territorial exclusivity, registered customs compliance, localized digital brand assets, and dedicated support for educational masterclasses and sommelier training.
How can wine trade buyers verify international winery credentials before signing agreements?
Professional buyers should conduct structured due diligence by evaluating audited exhibitor directories, reviewing historical production stability, demanding sample analysis certificates, and conducting face-to-face negotiations at dedicated business matching events.