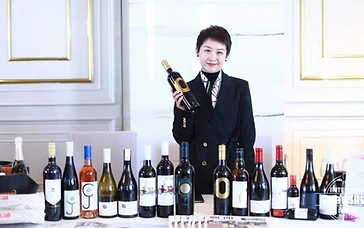
Industry Interview: A International winery on Emerging category demand
In this B2B trade interview, an international estate director dissects shifts in emerging wine categories, exploring no/low-alcohol growth, lighter reds, climate-resilient varietals, and actionable portfolio strategies for professional importers and buyers.
The global wine trade is navigating a structural pivot. Commercial buyers, on-premise beverage directors, and regional distributors are increasingly shifting attention toward non-traditional varietals, lighter-profile reds, and no/low-alcohol categories to capture dynamic consumer segments. According to the International Organisation of Vine and Wine (OIV), 2024 global wine consumption fell by 3.3% to an estimated 214.2 million hectolitres, reaching historic lows and leaving an inventory surplus of roughly 11 million hectolitres across major producing countries.
To understand how forward-looking producers are responding to these macro pressures, INTERWINE spoke with Julian Mercier, Commercial Director at Domaine Val d’Arceau, an export-focused multi-regional European winery group with active distribution across Asia, Europe, and North America. Mercier breaks down the shifting metrics of shelf turn, margin defense, and product development in an industry adapting to moderation and changing consumer palates.
The Shifting Buying Matrix: From Legacy Heritage to Segment Performance
INTERWINE: Julian, looking at procurement patterns over the last 18 months, traditional appellations appear under pressure while alternative categories show upward momentum. How does your export desk interpret this evolution?
Julian Mercier: For decades, international trade relied heavily on classification tiering: Grand Cru, DOCG, Reserve labels. While heritage labels maintain prestige, commercial velocity has moved toward style and functional drinking occasions. Data published in the IWSR 2024 Global Wine Trends Report indicates that low-alcohol wine volume expanded by +8% across top-10 global markets in 2023, primarily led by demand for 'better-for-you' attributes including lower ABV, reduced sugar, and mindful consumption.
At our estate, our partners in East Asia and Northern Europe are actively asking for products that bridge premium presentation with accessible drinkability. The traditional high-extraction, high-tannin reds that dominated sales sheets ten years ago now sit longer in distributor warehouses. Importers need fast-moving SKUs that resonate with younger legal drinking age (LDA) professionals who value refreshment, transparent labeling, and versatility with dining.
Emerging Category Demand Drivers (B2B Procurement View)
┌───────────────────────────────────────────────┐
│  Mindful Drinking & Wellness Drivers           │
│  - Sub-11% ABV Wines / Natural Acidity        │
│  - Certified Low/Zero Residual Sugar          │
├───────────────────────────────────────────────┤
│  Style Diversification                        │
│  - Chilled & Lighter Reds (Cabernet Franc)    │
│  - Indigenous / Climate-Resilient Varietals    │
├───────────────────────────────────────────────┤
│  Logistical Agility                           │
│  - Consolidated LCL Shipments / Pallet Testing │
│  - Rapid Stock Turnover on Casual On-Trade    │
└───────────────────────────────────────────────┘
Dissecting High-Growth Profiles: Lighter Reds and Indigenous Varietals
INTERWINE: Beyond dealcoholized wines, which styles are driving real volume and stable margins for your winery?
Julian Mercier: The fastest-growing red category in our portfolio is not Cabernet Sauvignon or Syrah; it is chilled, lighter-profile red wine—specifically Loire-style Cabernet Franc and unoaked indigenous grapes. As highlighted by Bibendum Wine Trends Report, up to half of top-tier on-trade wine lists have integrated versatile varietals like Cabernet Franc from both European and New World terroirs, driven by consumer migration toward fruit-forward, approachable dining wines.
We are also expanding production in indigenous varietals adapted to dry climates. Consumers are experiencing brand fatigue from standard supermarket varietals. When buyers curate portfolios, an autochthonous grape—whether it is a crisp Malvazija from the Adriatic corridor, a dry Furmint, or a mineral-driven white from Southern Europe—gives the on-trade sommelier a narrative that differentiates their list while safeguarding healthy pour margins.
Professional procurement teams looking to diversify their seasonal offerings can evaluate vetted international producers through the Exhibitor Directory or plan targeted on-site tasting sessions by navigating to Book Your Visit.
Managing Risk: Direct-to-Trade Hospitality vs. Wholesale Friction
INTERWINE: The Silicon Valley Bank State of the US Wine Industry Report 2024 emphasized that resilient producers must transition from transactional models toward relationship-driven trade strategies. How are you maintaining distributor alignment in this challenging landscape?
Julian Mercier: Importers are understandably managing inventory with extreme caution. IWSR records that still wine consumption in mainland China dropped by roughly 100 million cases between 2018 and 2023. Importers cannot afford dead stock. To support them, we no longer enforce rigid full-container-load (FCL) minimum order quantities (MOQs) for speculative emerging lines.
Instead, we collaborate through consolidated Less-than-Container Load (LCL) freight programs and back regional distributors with localized masterclasses and digital trade assets. We connect directly with regional accounts at professional trade expos where buyers test product viability before signing long-term container commitments. Commercial decision-makers can utilize specialized Business Matching frameworks to test micro-allocations directly with wineries, drastically cutting inventory risk.
Strategic Takeaways for Importers and Category Buyers
To capitalize on structural shifts while guarding balance sheets, procurement executives should adopt three practical strategies:
- Rebalance Portfolio Ratios: Allocate 15–20% of catalog real estate to high-growth emerging categories: sub-11% natural ABV whites, organic certified indigenous grapes, and chillable reds.
- Audit Commercial Velocity Over Accolades: Focus on inventory turn rate in casual dining and modern retail rather than traditional points-based prestige awards.
- De-Risk Procurement with Palletized Trials: Contract multi-SKU consolidated shipments before committing to single-varietal full containers, preserving liquidity while testing consumer acceptance.
Conclusion: Adapting Procurement to Modern Trade Realities
The contraction in overall wine volume reported across the international sector is not an indicator of market stagnation; rather, it reflects a decisive reallocation of capital toward innovative, approachable, and mindful wine categories. Wineries and commercial buyers that adapt their portfolios to cater to agile consumption patterns will capture sustainable market share. To discover premier international wineries and inspect the latest category innovations directly, Book Your Visit to connect with leading global producers.
Sources
- International Organisation of Vine and Wine (OIV) - Global Wine Consumption and Production 2024: https://www.oiv.int/
- IWSR Drinks Market Analysis - Five Key Trends Defining Opportunities in the Global Wine Market: https://www.theiwsr.com/insight/five-key-trends-defining-opportunities-in-the-global-wine-market-in-2025/
- Silicon Valley Bank - State of the Wine Industry Report: https://www.svb.com/trends-insights/reports/wine-report
- Bibendum Wine - On-Trade Trends and Demand Analysis: https://www.the-buyer.net/insight/whats-hot-in-the-on-trade-trade-wit-bibendums-new-trends-report
Key Takeaways
- —According to OIV 2024 reporting, global consumption contracted 3.3% to 214.2 mhl, necessitating agile portfolio diversification.
- —IWSR figures indicate low-alcohol wine volumes grew +8% across top-10 global markets in 2023, establishing no/low ABV as a resilient growth driver.
- —B2B buyers are prioritizing lighter, food-friendly reds like Cabernet Franc and indigenous varietals to satisfy younger LDA drinking trends.
- —Distributors are shifting procurement away from rigid full-container commitments toward consolidated LCL freight and flexible MOQ structures.
- —Importers can leverage commercial business matching programs to secure high-margin, climate-resilient allocations.
Frequently Asked Questions
What emerging wine categories are generating the strongest on-trade velocity?
On-trade venues are experiencing sustained demand for low-ABV (under 11%) whites, crisp sparkling wines, chilled lighter reds such as Cabernet Franc, and indigenous varietals that offer unique menu storytelling and strong per-pour margins.
How can wine importers mitigate the financial risk of introducing new wine styles?
Importers can mitigate risk by negotiating lower Minimum Order Quantities (MOQs), utilizing Less-than-Container Load (LCL) consolidated freight, and attending targeted business matching exhibitions to test small-scale allocations before scaling orders.
Why is the low-alcohol wine category expanding despite overall volume declines?
IWSR research demonstrates that low-alcohol wine expanded by +8% across key markets due to younger legal drinking age consumers adopting mindful moderation, seeking functional health benefits without abandoning wine ritual and social dining.
How are international wineries modifying production to support commercial buyers?
Wineries are actively adjusting harvesting times to preserve natural acidity, reducing oak extraction, adopting certified organic and vegan practices, and offering flexible marketing support to help distributors move emerging SKUs.